Shares and ETFs
Long and shortShares, ETFs and depositary receipts across markets in several countries, held both long and short. This is the sleeve with the largest number of positions.
L
Long positions
S
Short positions
Marketing communication. Capital at risk. Produced by FRAMONT & Partners Management Ltd. Not investment advice, not a solicitation, not a public offering. The strategy uses leverage, derivatives and short selling, and can lose value quickly. Read the Key Information Document and the prospectus before taking any decision.
A result built so that it does not depend on the direction of equity markets. It can be positioned short as well as long.
Value Edge is a segregated portfolio that hosts the SnowWhite strategy, developed by Giovanni Zibordi. Trading is discretionary and spread across many small positions: shares from several countries held both long and short, futures on equity indices and government bonds, options, currencies and commodities. Positions offset each other and sit on different time horizons, which is why the strategy can use leverage while remaining lightly concentrated.
Leverage amplifies losses as well as gains. The instrument is newly issued and has no track record of its own. Capital is at risk and you may lose the full amount invested.
SnowWhite does not start from a forecast on the equity index. It starts from a wide set of independent positions, held both long and short across different markets and horizons, which tend to offset one another. The stated objective is a return that does not follow equity markets, not a return above equity markets in a rising phase.
Leverage is possible precisely because the positions are many, small and different from one another.
Decisions are discretionary. The only systematic tool used is Tom DeMark's Sequential indicator, on which the strategy developer has written for years. Exiting a losing position is governed by a quantitative rule: the impact of any single position on account value must not exceed 2%.
Build a result that depends on the selection and management of individual positions rather than on the direction of equity indices.
Spread risk across shares from different countries, government bonds through futures, commodities and currencies, with holding periods from intraday to several weeks.
Apply an exit rule based on the position's percentage impact on the account, with a maximum drawdown stated as acceptable at 13%.
Objectives describe intent. They are not a promise, a target return or a guarantee. The strategy can lose value in any market environment, including when equity markets rise.
The Key Information Document and the prospectus, provided by FRAMONT on request, are the only binding sources on costs, risks and instrument identifiers.
The universe is the one accessible through Interactive Brokers and set out in the portfolio's trading mandate. Every position is in liquid instruments traded on regulated markets. There are no directly held corporate bonds, no illiquid instruments and no off market instruments.
Shares, ETFs and depositary receipts across markets in several countries, held both long and short. This is the sleeve with the largest number of positions.
Futures on equity indices and government bonds. No bonds are held directly: fixed income exposure is taken through futures.
Options both long and short on the same underlyings, plus currencies and commodities through futures. They modulate risk and diversify the sources of return.
Cash can reach 100% of the portfolio. The mandate also requires the weight of the cash position, net of derivative margin, to stay above -200%.
Trading mandate limits. The sum of the exposures of all portfolio constituents, excluding FX, CFDs and derivatives, is capped at 300%. The weight of the cash position, net of derivative margin, must remain above -200%. Whenever cash is below 50%, the portfolio is diversified into at least 4 assets. The composition and respective weights are published monthly on the issuer's website. Rebalancing may take place at any time, including intraday.
The book has no fixed weights. The three sleeves coexist with different durations and intensities and are sized position by position. Select a sleeve to see its typical horizon, number of positions, use of leverage and indicative weight. The bands describe operating intent, not binding limits or weights committed to investors.
Shares and depositary receipts across several markets, held both long and short, together with options written on the same underlyings. This is the sleeve with the largest number of simultaneous positions and the longest holding period.
Band scale, left to right: minimal to dominant
Futures on equity indices and government bonds, used both to take positions and to offset the risk carried by the rest of the book. This is the shortest horizon and can come down to a single session.
Band scale, left to right: minimal to dominant
Currencies and commodities, accessed through futures. They diversify the sources of return and hedge the currency exposure of the book, which is managed on a discretionary rather than systematic basis.
Band scale, left to right: minimal to dominant
Illustrative representation. The actual composition is decided case by case and will differ from anything shown here. The binding exposure limit is the one set in the trading mandate, at 300%.
The decision to open, size and close each position is discretionary and stays with the strategy developer within the boundaries of the mandate.
The only formalised system in use is Tom DeMark's Sequential indicator, applied as a support in reading market timing.
Closing a losing position is determined by its impact on account value, set at 2% as a stop loss. In particularly turbulent markets the exit can be filled at a price worse than the level intended.
The maximum leverage stated by the strategy developer is four times, and it comes from the sum of many different positions rather than from a few amplified bets. Above this operating setup sit the binding limits of the mandate and the manager's powers of intervention.
Some are operating settings chosen by the strategy developer, others are contractual limits in the mandate. The distinction matters: the latter are binding.
The exit on a loss is based on the impact of the single position on account value, set at 2% as a stop loss.
The level stated as acceptable by the strategy developer. It is not a guarantee: actual losses can exceed it.
Contractual limit on the sum of the exposures of the portfolio constituents, excluding FX, CFDs and derivatives.
Whenever cash is below 50% of the portfolio, positions are spread across at least four assets.
Typical operations involve up to fifty simultaneous positions across different markets and instruments, held both short and long where equities are concerned. With a 2% exit rule per position, no single trade can determine the outcome of the portfolio on its own.
Long and short positions across shares, bonds, commodities and currencies, on different horizons, tend to offset each other and reduce dependence on any single market.
The manager, through the Risk Manager or the Investment Committee, holds exclusive authority to suspend trading and can revoke the trading authority held with the broker.
SnowWhite does not come from a model optimised on historical series. It comes from decades of market analysis and continuous trading activity, and its rules were defined, corrected and maintained on orders actually executed in the market, with capital genuinely at risk. The distinction is substantive: a live portfolio incorporates the liquidity available at the moment of the order, trading costs, the gap between expected and executed price, and decisions taken while the market is moving. No simulation reproduces those elements.
A backtest tells you how a rule would have behaved. An executed order tells you how the person applying it behaves.
The only systematic tool in use is Tom DeMark's Sequential indicator, the subject of years of study and writing by the strategy developer. Everything else is judgement applied case by case, within written limits.
The 2% impact exit per position, the drawdown threshold considered acceptable and the spread across a large number of positions are not simulation parameters: they are rules applied to executed trades, across different market phases.
Market analysis, trading indications and portfolio logic have been published since 2022, with a freely accessible archive at giovannizibordi.ghost.io. Anyone assessing the instrument can read how the reasoning was built over time, not only the final outcome.
Value Edge is newly issued and has no track record of its own: no past performance data is published on this page. The documentation supporting the development of the strategy, including the data perimeter, the calculation methodology and the related warnings, is provided by FRAMONT on request together with the Key Information Document and the prospectus. The instrument operates inside a regulated structure, with its own costs, mandate limits and controls, which can produce results different from any previous operating experience. Past results, however calculated, are not a reliable indicator of future results. Capital is at risk.
The separation of roles is the most important point on this page. The person who developed the strategy and the entity that carries regulatory responsibility are not the same.
Giovanni Zibordi is the developer of the SnowWhite strategy and acts as a support services provider: he transmits and executes orders on the execution account under a Trading Authority, within the limits of the trading mandate. He does not provide investment advice and any recommendation of his is non binding.
FRAMONT & Partners Management Ltd, authorised by the MFSA as an Alternative Investment Fund Manager, retains full and exclusive authority over investment decisions and strategy, and assumes regulatory responsibility for the structure.
The manager's Risk Manager and Investment Committee hold exclusive authority to suspend trading in the event of breaches of limits or risk conditions, and to revoke the Trading Authority held with the broker.
The instrument is issued as a segregated portfolio within a dedicated issuance structure, with its own identifiers, NAV calculation administrator, depositary and paying agent. The issuer is iMaps and the instrument is listed on Borse Stuttgart.
The portfolio composition and respective weights are published monthly on the issuer's website. The Key Information Document sets out the risk indicator, the performance scenarios and the full cost breakdown.
| Legal name | Value Edge Segregated Portfolio |
| Strategy trade name | SnowWhite |
| ISIN | DE000AMC0BZ5 |
| Manager | FRAMONT & Partners Management Ltd |
| Base currency | EUR, currency hedging is not systematic |
| Permitted instruments | Shares, ETFs and depositary receipts long and short, bonds long and short, warrants long, options long and short, futures long and short, mutual funds and alternative funds long, cash up to 100% |
| Maximum exposure | 300%, excluding FX, CFDs and derivatives |
| Borrowing limit | Cash weight, net of margin, always above -200% |
| Rebalancing | At any time, including intraday |
| ISIN, KID, prospectus | On request from FRAMONT |
| Ongoing costs | Set out in the KID |
| Performance related fees | Set out in the KID and the prospectus |
| Entry and exit charges | Set out in the KID |
| Trading costs | Broker commissions and charges, accounted for within the NAV |
| Binding source | Key Information Document and prospectus |
| How to obtain them | On request from FRAMONT, before any decision |
Fee levels are not shown on this page. The Key Information Document gives the complete and binding presentation of costs, including their impact on return, and is the only source to rely on.
Under MiFID II product governance rules the instrument is aimed at a defined target market. It is built for investors seeking a result that is not tied to equity market direction and who accept fluctuation in the order of 10% of the amount invested, in the knowledge that actual fluctuation can be greater.
The positive target market covers retail and professional clients with knowledge and experience of listed instruments, derivatives and the use of leverage, a risk tolerance consistent with medium to high volatility, and an investment objective compatible with a discretionary multi market strategy. The negative target market covers investors requiring capital protection, investors who cannot bear losses and conservative profiles. The final target market is aligned with the KID and communicated to distributors, who remain responsible for their own suitability assessment. Nothing on this page is a personal recommendation.
This page is a marketing communication. It is not an official source of instrument documentation.
The PRIIPs compliant KID sets out the nature of the instrument, the summary risk indicator, the performance scenarios and the full cost breakdown. Read it before any investment decision.
Request from FRAMONTCovers the structure, the investment policy, the fee mechanics and all terms and conditions of the segregated portfolio.
Request from FRAMONTThe ISIN, the issuer, the administrator calculating the NAV, the depositary, the paying agent and the listing details are provided directly by FRAMONT.
Contact FRAMONTOfficial source. For the ISIN, the KID, the prospectus, subscription details and valuation information, contact FRAMONT & Partners Management Ltd at gianluigi.montagner@framontmanagement.com. FRAMONT & Partners Management Ltd is authorised and regulated by the Malta Financial Services Authority.
A summary of the principal risks, not a complete list. The Key Information Document and the prospectus contain the full disclosure. Risks and benefits are given equal prominence on this page.
There is no capital protection and no guaranteed return. You may lose part or all of the amount invested.
The strategy states a maximum leverage of four times and the mandate allows total exposure up to 300%. Leverage amplifies losses as well as gains.
The use of futures and options, including written options, involves margin risk, expiry risk and the risk of losses larger than the premium received.
Short positions carry a theoretically unlimited potential loss and can be hit by sudden rallies or by regulatory restrictions on short selling.
The strategy is discretionary and operationally entrusted to Giovanni Zibordi. His unavailability, or the revocation of the Trading Authority, directly affects the running of the portfolio.
The base currency is the euro, but positions sit in markets denominated in other currencies. Hedging is done with futures and is not systematic, so part of the currency exposure can remain open.
With no system automatically determining the choices, the outcome depends on the judgement of the person trading, whose timing and direction can be wrong.
A book with many simultaneous positions carries higher trading costs, greater operational complexity and more points where execution can go wrong.
Offsetting between positions in different markets holds as long as those markets move independently. In stressed conditions correlations tend to rise and the diversification benefit shrinks.
Value Edge is newly issued and has no track record of its own. The operating experience behind the development of the strategy relates to a context different from that of the instrument, which has its own costs, mandate limits and controls, and does not anticipate future performance.
Under abnormal market conditions the bid ask spread can widen materially and liquidity can be reduced.
The instrument depends on the issuer, the broker and the service providers. A failure at any of them can affect value or access to the position.
The strategy developer receives a share of the performance fee generated by the portfolio. This can create an incentive to take more risk. The mitigation lies in the mandate limits and in the manager's suspension powers.
The strategy developer publishes analysis and trading signals on his own channels. What may be published, with what delay and in what detail, is governed by a Communications Policy agreed with the manager.
Changes in law, regulation or tax treatment may affect the instrument, its structure or your net return.
The fees charged by the instrument, the issuer charges and the trading costs reduce the return, and the part that is not performance linked is due in negative periods too. The full breakdown, including the impact on return, is in the KID.
The list above is a non exhaustive summary provided for information. It does not replace the risk disclosures in the Key Information Document and the prospectus, which should be read in full before any decision. If you are uncertain, consult a licensed independent financial adviser. FRAMONT & Partners Management Ltd does not provide personal investment advice. Past results, however calculated, are not a reliable indicator of future results. Capital is at risk.
Value Edge is the legal name of the segregated portfolio, SnowWhite is the trade name of the strategy applied within it. Management and regulatory responsibility sit with FRAMONT & Partners Management Ltd, an MFSA authorised AIFM. Capital is at risk.
Shares, ETFs and depositary receipts both long and short, bonds long and short, warrants long, options long and short, futures long and short, mutual funds and alternative funds long, and cash up to 100%. The universe is the one accessible through Interactive Brokers and is limited to liquid instruments. No corporate bonds are held directly: fixed income exposure is taken through government bond futures.
It is discretionary. The only systematic tool used is Tom DeMark's Sequential indicator. The quantitative rule in force concerns exiting losing positions, with a maximum impact of 2% on account value per single position.
The stated maximum leverage is four times and comes from the sum of many different positions. The trading mandate sets a binding limit on total exposure at 300%, excluding FX, CFDs and derivatives, and requires the cash weight, net of margin, to stay above -200%.
The strategy was developed by Giovanni Zibordi, analyst and trader, MBA, founder of cobraf.com. He acts as a support services provider and transmits orders on the execution account under a Trading Authority. He is not the manager of the instrument and does not provide investment advice: investment decisions, risk oversight and regulatory responsibility sit with FRAMONT & Partners Management Ltd.
No performance data is published on this page. Value Edge is newly issued and has no track record of its own. The strategy was however developed and verified on orders actually executed in the market rather than on a theoretical backtest: the supporting documentation, including the data perimeter, the calculation methodology and the warnings, is provided by FRAMONT on request together with the KID and the prospectus.
The portfolio can take short as well as long positions, in shares and in index futures, which is why its result does not depend on the direction of equity indices. It is not a hedging instrument, though: it is not built to rise when equity markets fall, and it can lose value in any market environment, including falling ones. Capital is at risk.
The costs of the instrument, including ongoing and performance related fees, are set out in the Key Information Document and the prospectus, which are the binding sources and also show the impact of costs on return. The KID is provided by FRAMONT on request and must be read before any decision. For that reason no fee levels are shown on this page.
His channels publish market and macro analysis, along with trading indications aimed at a general audience and without position sizing. These are not the instrument's positions and should not be read as such: any real time overlap between the two is governed by a Communications Policy agreed with the manager, precisely to avoid market abuse issues and unfair treatment of investors. Official product information comes only from FRAMONT.
The ISIN, the KID, the prospectus, the issuer details and the listing details are provided exclusively by FRAMONT & Partners Management Ltd at gianluigi.montagner@framontmanagement.com.
Answers are a summary for information only, are not investment advice and do not replace the KID or the prospectus.
Giovanni Zibordi is an analyst and trader, holding an MBA from the University of California, Los Angeles. He is the developer of the SnowWhite strategy.
Since 1998 he has been the founder and operator of cobraf.com, an investment and trading advisory site with a blog and forum, later joined by X channels and Substack newsletters. Publishing his trades and results transparently is a long standing habit of his activity.
Before moving to analysis and trading he worked in corporate strategy consulting: manager at Booz Allen in Milan between 1993 and 1994, on projects for Alitalia and Corning, and at Telos Management in Milan between 1991 and 1992, on projects for the IRI group, Italimpianti and Ansaldo.
On the academic side, after a degree in Economics from the University of Modena and three years of doctoral research in Economics at La Sapienza in Rome, he moved to UCLA where he completed a Master in Business Administration between 1988 and 1990.
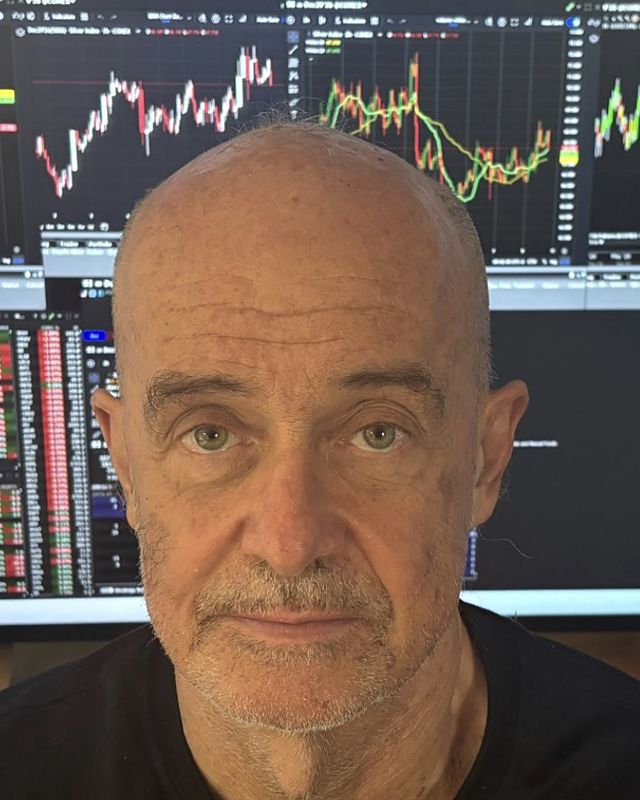
Giovanni Zibordi developed the strategy and handles order execution. He is not the manager of the instrument. Investment decisions, risk management, oversight and compliance sit with FRAMONT & Partners Management Ltd as MFSA authorised AIFM. The professional experience and academic credentials listed describe the person who developed the strategy: they are not a regulatory qualification and are not an indication of the instrument's future results.
Market and economic analysis. Around 7,900 followers. x.com/GiovanniZibordi
Paid channel, 55 euro, with around 90 subscribers. Trading indications without position sizing, aimed at a general audience. x.com/GZibordiCobraf
Archive since 2022 of the paid channel content, freely accessible. giovannizibordi.ghost.io
Newsletters on markets and the economy. zibordi.substack.com and biancaneve.substack.com
Investment and trading advisory site, blog and forum, active since 1998. cobraf.com
Daily commentary on markets and on the rationale of the trades, weekly commentary on management results. All recurring content goes through the manager's pre approval process.
The strategy developer receives a share of the performance fee generated by the segregated portfolio. This is a conflict of interest and is disclosed here, as well as being repeated whenever the product is mentioned on his channels. The mitigation lies in the limits of the trading mandate, in the suspension powers of the Risk Manager and the Investment Committee, and in the manager's ability to revoke the Trading Authority.
Every published item and every promotional material relating to the product, on this page as on the strategy developer's channels, is submitted to FRAMONT for approval before publication, and the same applies to later amendments. The personal channels link to this official page: editorial responsibility for the product stays with the manager.
FRAMONT brings MFSA authorisation, AIFMD compliance and the operating infrastructure needed to run a discretionary strategy inside a regulated perimeter.
Authorised by the Malta Financial Services Authority as an Alternative Investment Fund Manager under the AIFMD, with full EU regulatory standing.
The manager retains full and exclusive authority over investment decisions and strategy and monitors that trading stays within the mandate and applicable regulation.
An independent Compliance Officer, a Risk Manager and an Investment Committee provide ongoing oversight. AML and KYC obligations, regulatory reporting and MFSA filings are handled in house.
Depositary, administration, audit and reporting platforms support transparent management of the portfolio.
Beyond this instrument, FRAMONT operates an MFSA authorised platform for AIFs, AMCs and ETIs. More at framontmanagement.com.
The vehicle's transparency and reporting standards apply, with monthly publication of the portfolio composition and cost disclosure through the KID.
The KID, the prospectus, the ISIN and the listing details are provided directly by FRAMONT & Partners Management Ltd.
Contact FRAMONT & Partners Management Ltd for the Key Information Document, the prospectus, the ISIN and the listing details.
For the KID, the prospectus, the ISIN and subscription information. All official documents are provided exclusively through FRAMONT.
gianluigi.montagner@framontmanagement.comFor distribution agreements, institutional allocations or information on the FRAMONT platform for EU investment vehicles.
www.framontmanagement.comDragonara Business Centre, 5th Floor
Dragonara Road, San Giljan STJ 3141
Malta
+356 20105592
If you run a strategy and need a regulated EU wrapper, the MFSA authorised FRAMONT platform covers AIF, AMC and ETI structures.
EU investment vehiclesThis page is a marketing communication produced by FRAMONT & Partners Management Ltd. It is not investment advice, a solicitation or an offer to buy or sell any financial instrument. The strategy uses leverage, derivatives and short selling and can lose value rapidly. The instrument is newly issued and has no track record of its own: no performance data is published on this page. Capital is at risk. Read the KID and the prospectus before investing. FRAMONT & Partners Management Ltd is authorised and regulated by the Malta Financial Services Authority as an Alternative Investment Fund Manager.